Is VC really heading back to California?
In the first quarter of 2026, 83% of venture capital dollars went to companies in the US. But there are three major forces behind the data that are distorting the picture. Let’s take a closer look.
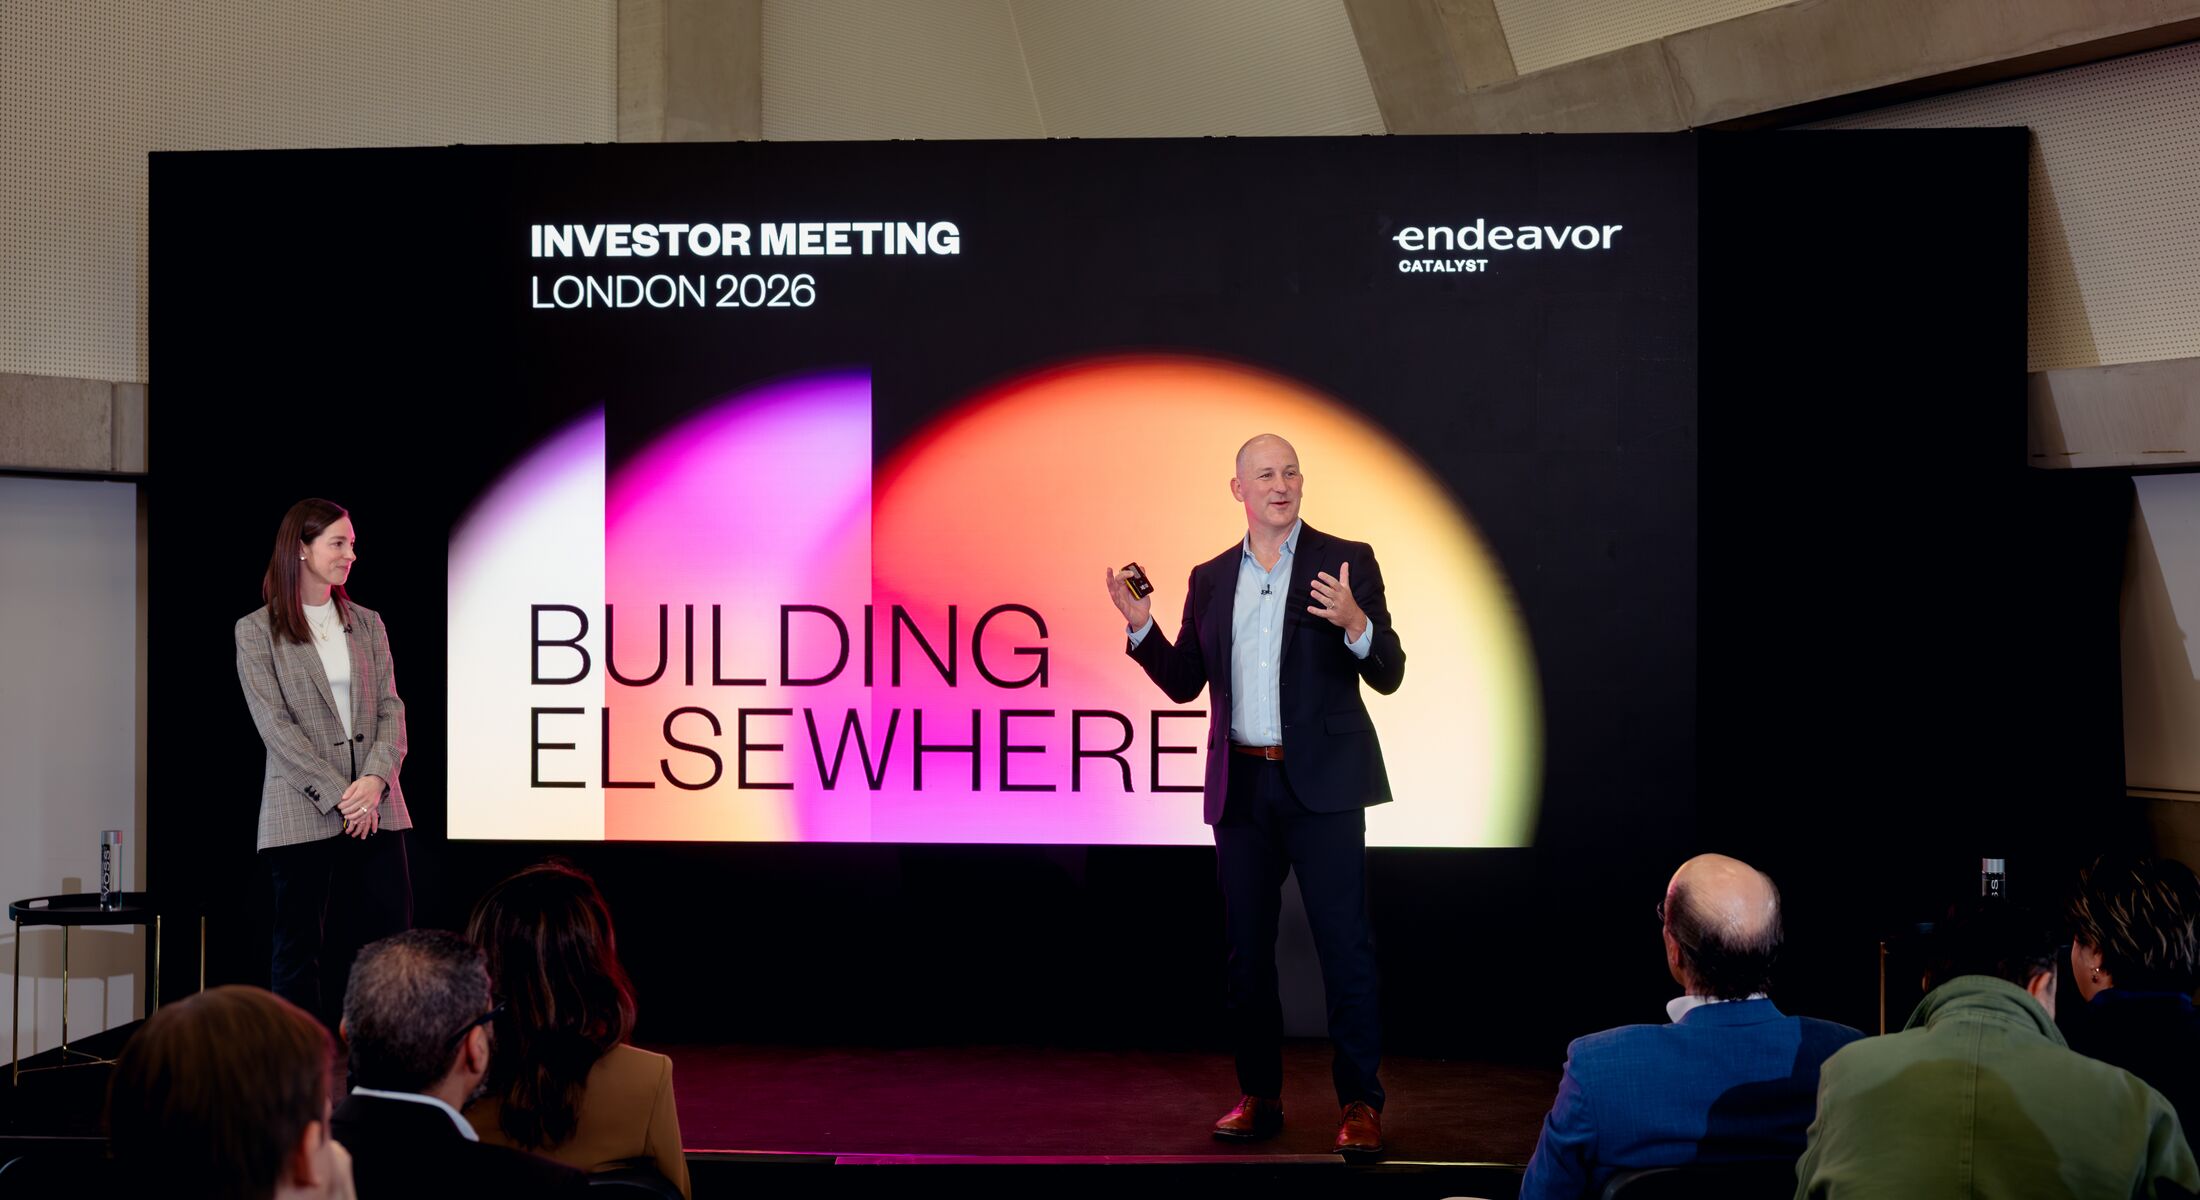
The entrepreneurial scene’s geographic reach is shrinking. That’s according to Y Combinator CEO Garry Tan, who told Fortune magazine that these days, “you sort of have to be in San Francisco”. Explaining his strategy behind the startup accelerator’s headquarters move from Mountain View to San Francisco, Tan pointed to the rise of AI and data that indicates startups in San Francisco might be more successful than their peers.
It’s a statement contrary to everything Endeavor believes: that there is great entrepreneurial talent everywhere and that global success can originate far from the USA’s West Coast.
However, the VC data might just back Tan up. Over the past two decades, VC dollars invested Elsewhere (outside of the major startup hubs in the US and China) grew from 10% of the market to 60% by 2024. Last year, that trend reversed, with 64% of VC dollars going to US companies. In the first quarter of 2026, we hit “peak San Francisco”: 83% of VC dollars went to US companies, totaling $300B. Almost all of those US dollars — three quarters of them — went to just four American companies: OpenAI, Anthropic, xAI (before it became part of SpaceX), and Waymo.
The surface level of this data looks pretty damning. But dive deeper, and it paints a different picture — one that shows a strong continued trajectory of growth for Elsewhere founders amongst a changing VC landscape.
California isn’t the heart of entrepreneurial success and ambition. But it is a hub for three major shifts that are changing the investment playbook.
Halfway through 2026, it’s time to take a clear look at them.
Shift One: Late-stage private markets are the new public markets
Before SpaceX’s IPO in June this year, the largest tech IPO in history in terms of raised capital was Alibaba, all the way back in 2014: $21.8B. That seems positively modest compared to SpaceX’s blockbuster $75B, but it was the culmination of a series of then-massive tech IPOs: Facebook’s $16B in 2012 and SoftBank’s $21B in 2018.
But compare those IPOs to the private VC rounds from the first quarter of this year. xAI raised $20B in January, Anthropic raised $30B in February, and OpenAI raised a whopping $122B — larger than SpaceX’s IPO — in March.
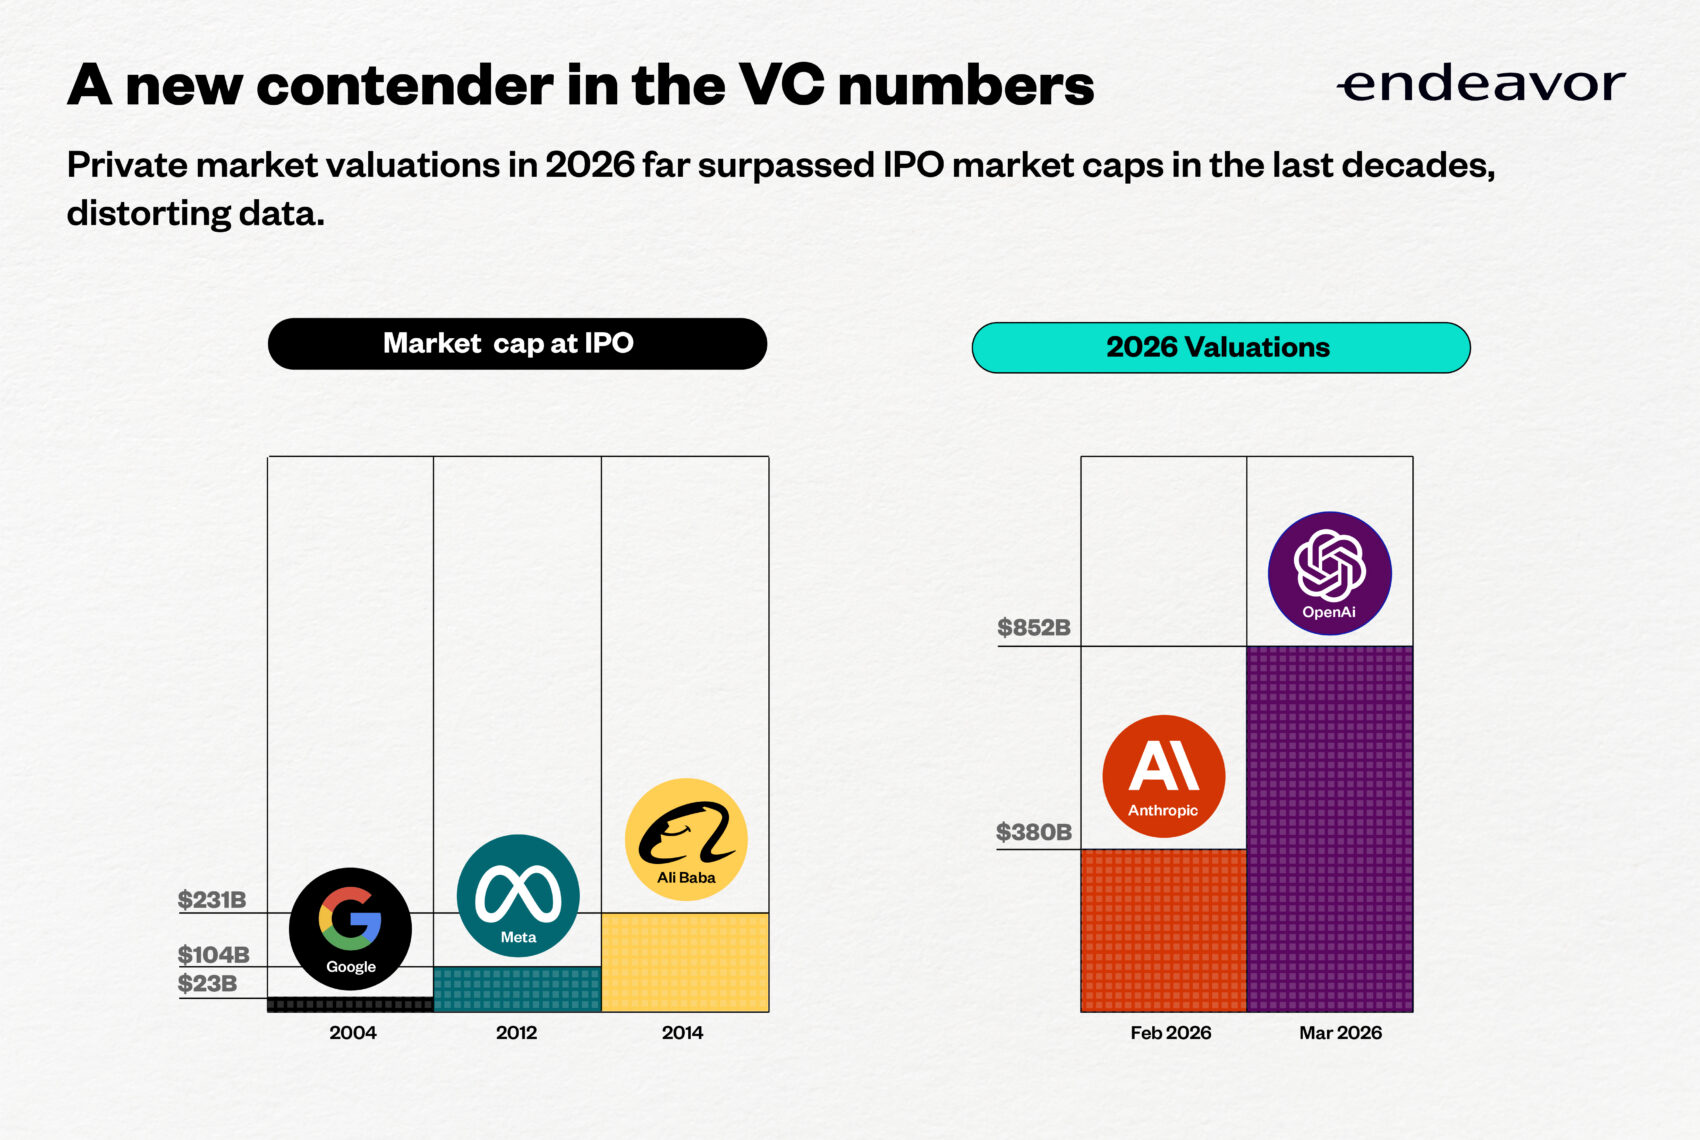
In essence, 2026 private market valuations are far surpassing the IPO market caps of the past decades. These massive individual companies are so much bigger in the private markets that they’re distorting the data on venture capital, by attracting numbers that we would never before have counted as part of the venture world.
Shift Two: Venture capital is bifurcating as an asset class
When we read the venture capital data we shared above, we read it as one bucket of money. But the rise of mega funds — multi-stage, multi-billion dollar, multi-sector — means that we’re seeing an increasing bifurcation of venture capital itself. And the data shows this, too.
The top ten venture firms — Andreessen Horowitz, Thrive Capital, Lightspeed, and their compatriots — accounted for more than half of all LP fundraising in the eighteen months from the beginning of 2025 to mid-2026. Some data suggests that as much as 80% of all venture capital dollars are going to these top ten firms, who now manage over half a trillion dollars, putting them on par with the top growth equity firms like General Atlantic, Warburg Pincus, Silver Lake, and co, and rivaling them for size.
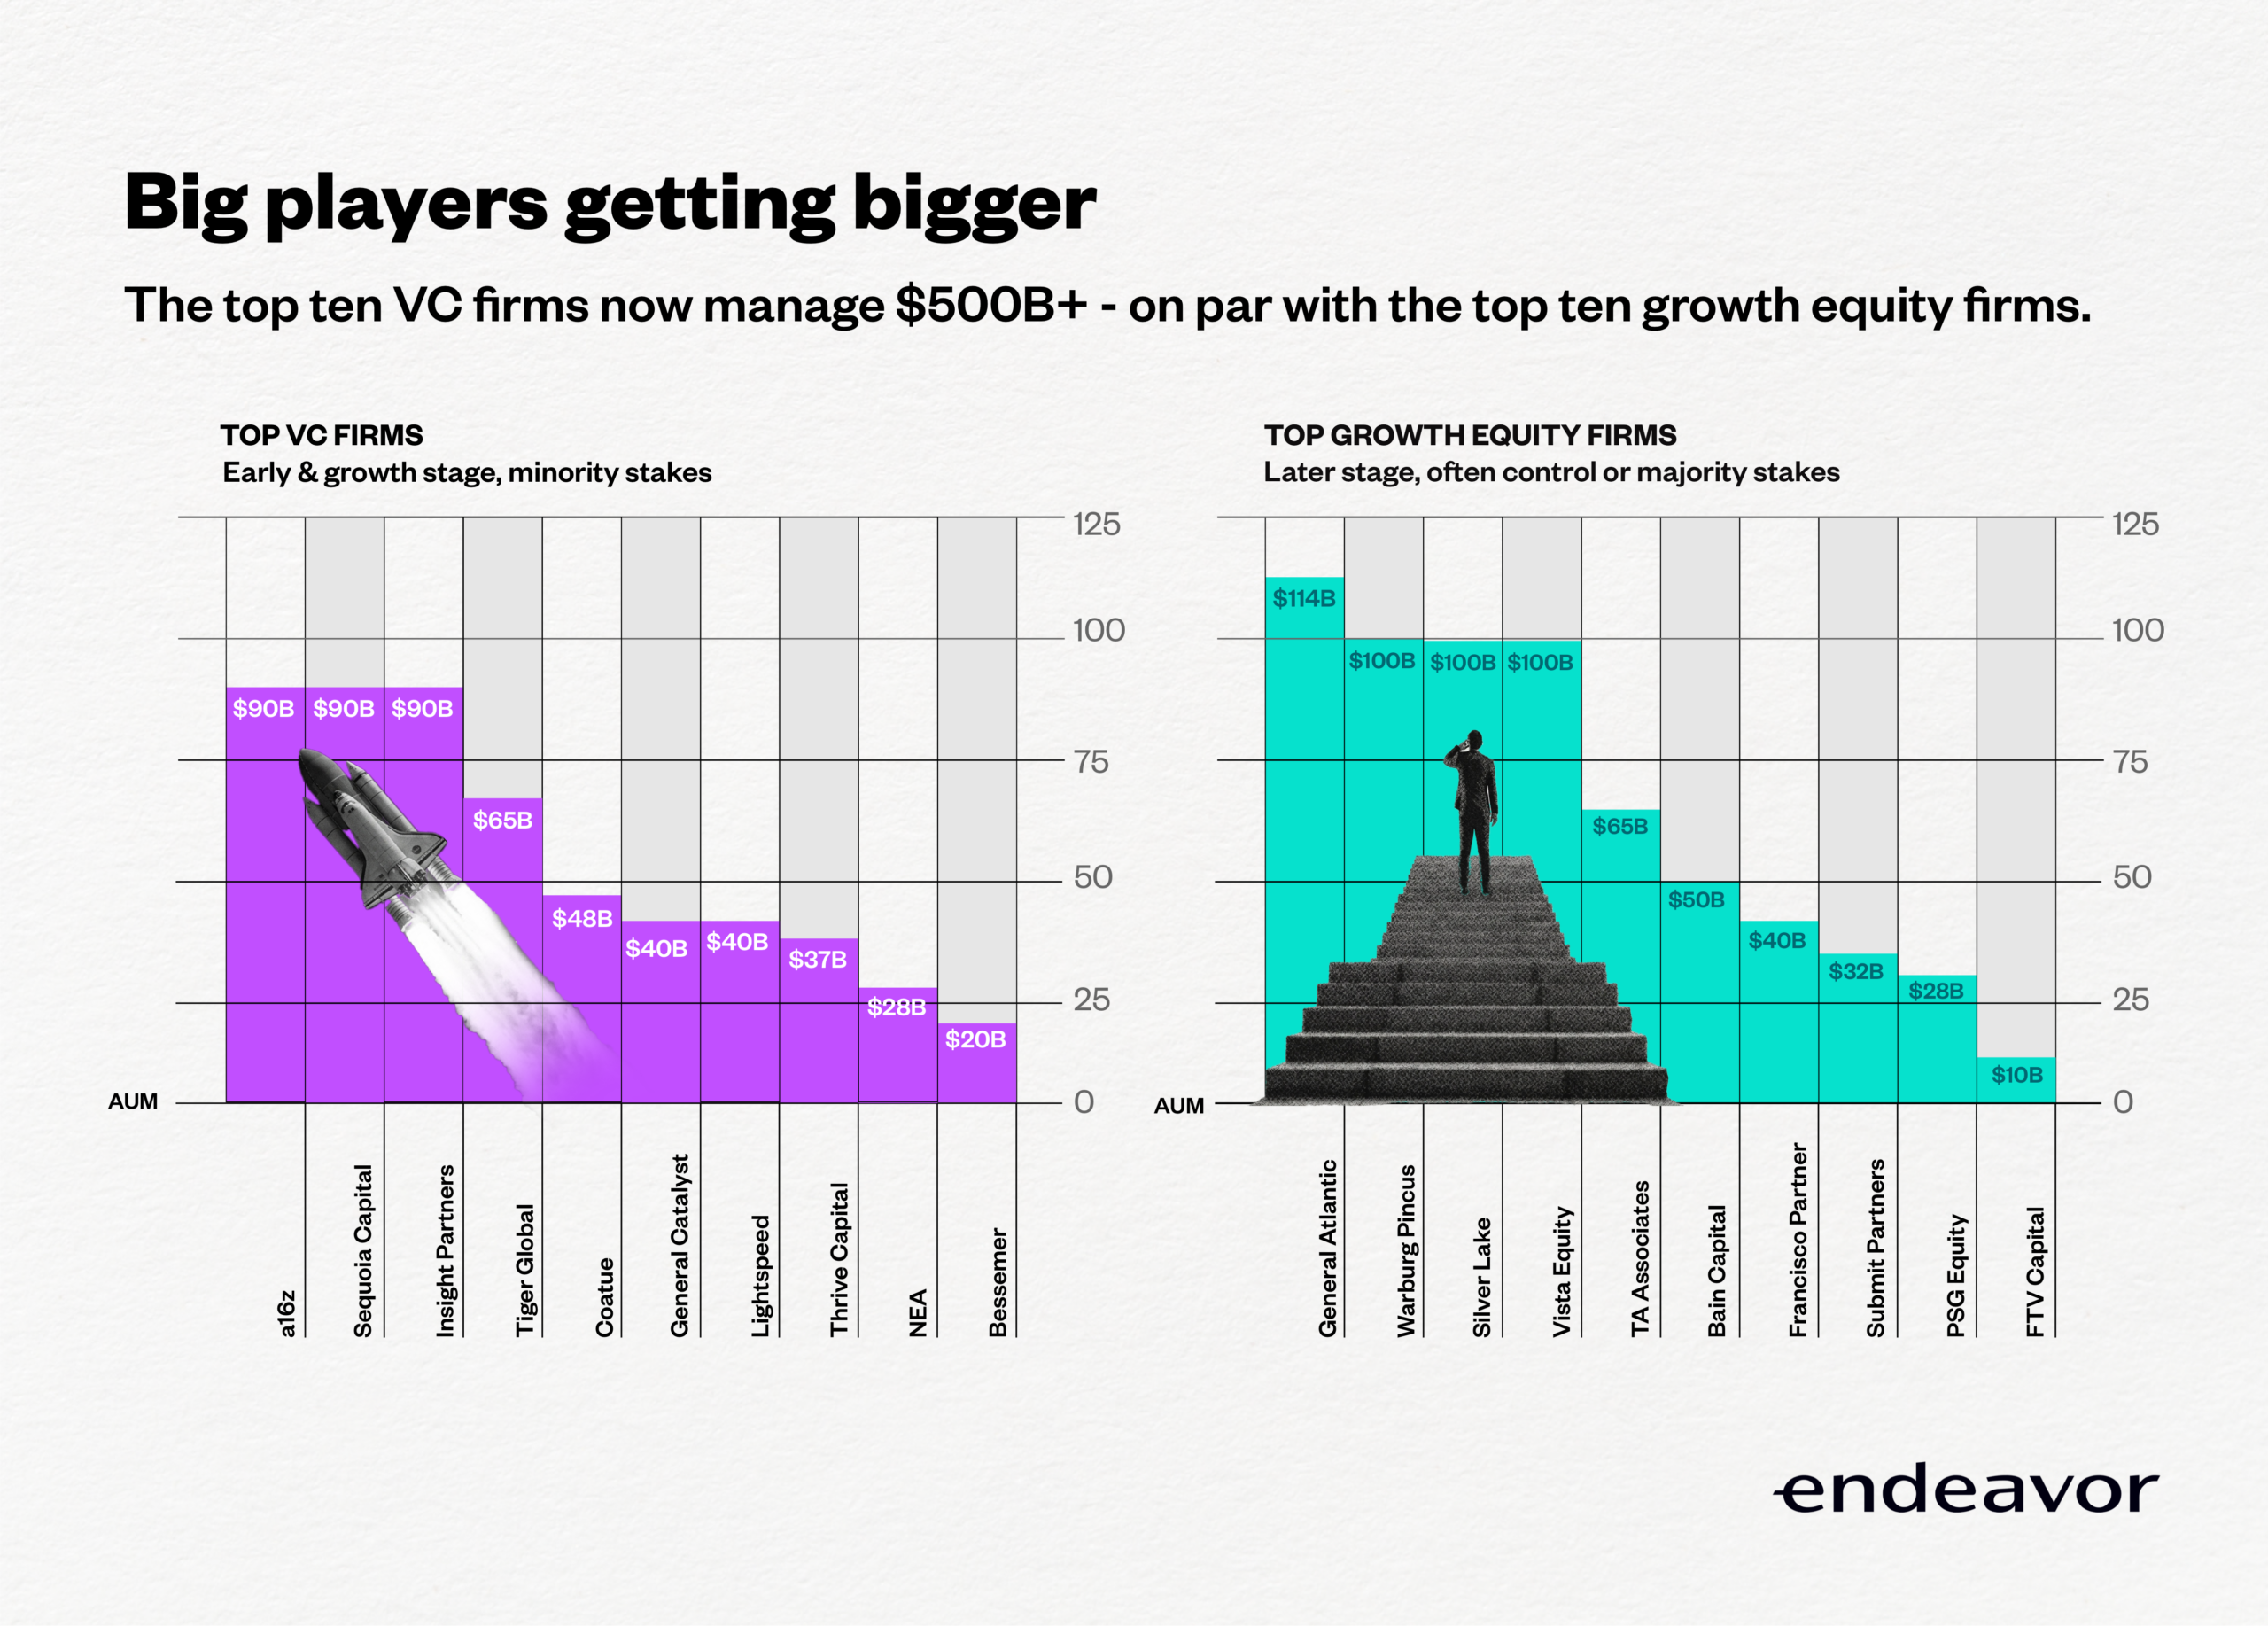
At this level, venture is a different ballgame. Samir Kaji, CEO of tech platform Allocate and host of podcast Venture Unlocked, said, “The barbell between large and small firms is as wide as it’s ever been. These are genuinely two distinct asset classes now, and LPs should treat them that way.”
While there are still funds practicing venture the way it has been traditionally done — including Benchmark, Union Square, and our very own Endeavor Catalyst — using funds of under $500M for early stage investments with the best founders, the second asset class isn’t just twice the size; they’re ten times larger, or more.
Their goals are correspondingly different. Rather than traditional venture capital strategy, they’re not looking for multiples on invested capital, but instead the pure tonnage of dollars they can put to work. The traditional alpha investment strategy — returns above the market average, generated by skill — is an element of these large venture moves, but they’re also increasingly delivering beta returns, which track the market.
Rather than picking winners, they’re investing everything in the market in the same companies, with big checks.
Shift Three: A few actors are financing the major AI infrastructure build
Those massive rounds from OpenAI, Anthropic, XAI, and Waymo made headlines. The people who actually invested in them tend to be buried a little deeper in the copy — but they’re worth observing.
The majority of funding for these major rounds came from hyperscalers and global sovereign wealth funds. 90% of OpenAI’s $122B round came from Amazon, Nvidia, and SoftBank. Andreessen Horowitz contributed too, ensuring there is venture capital in the mix, but the bulk of the investment comes from hyperscaling companies and other late stage investors.
Anthropic shows a similar story, with a $30B round primarily led by sovereign wealth funds and late stage funds. 70% of Waymo’s $16B round came from Google — who already majority owned them. The $20B XAI round contained almost no traditional venture capital firms, and was instead majorly led by just one man: Elon Musk.
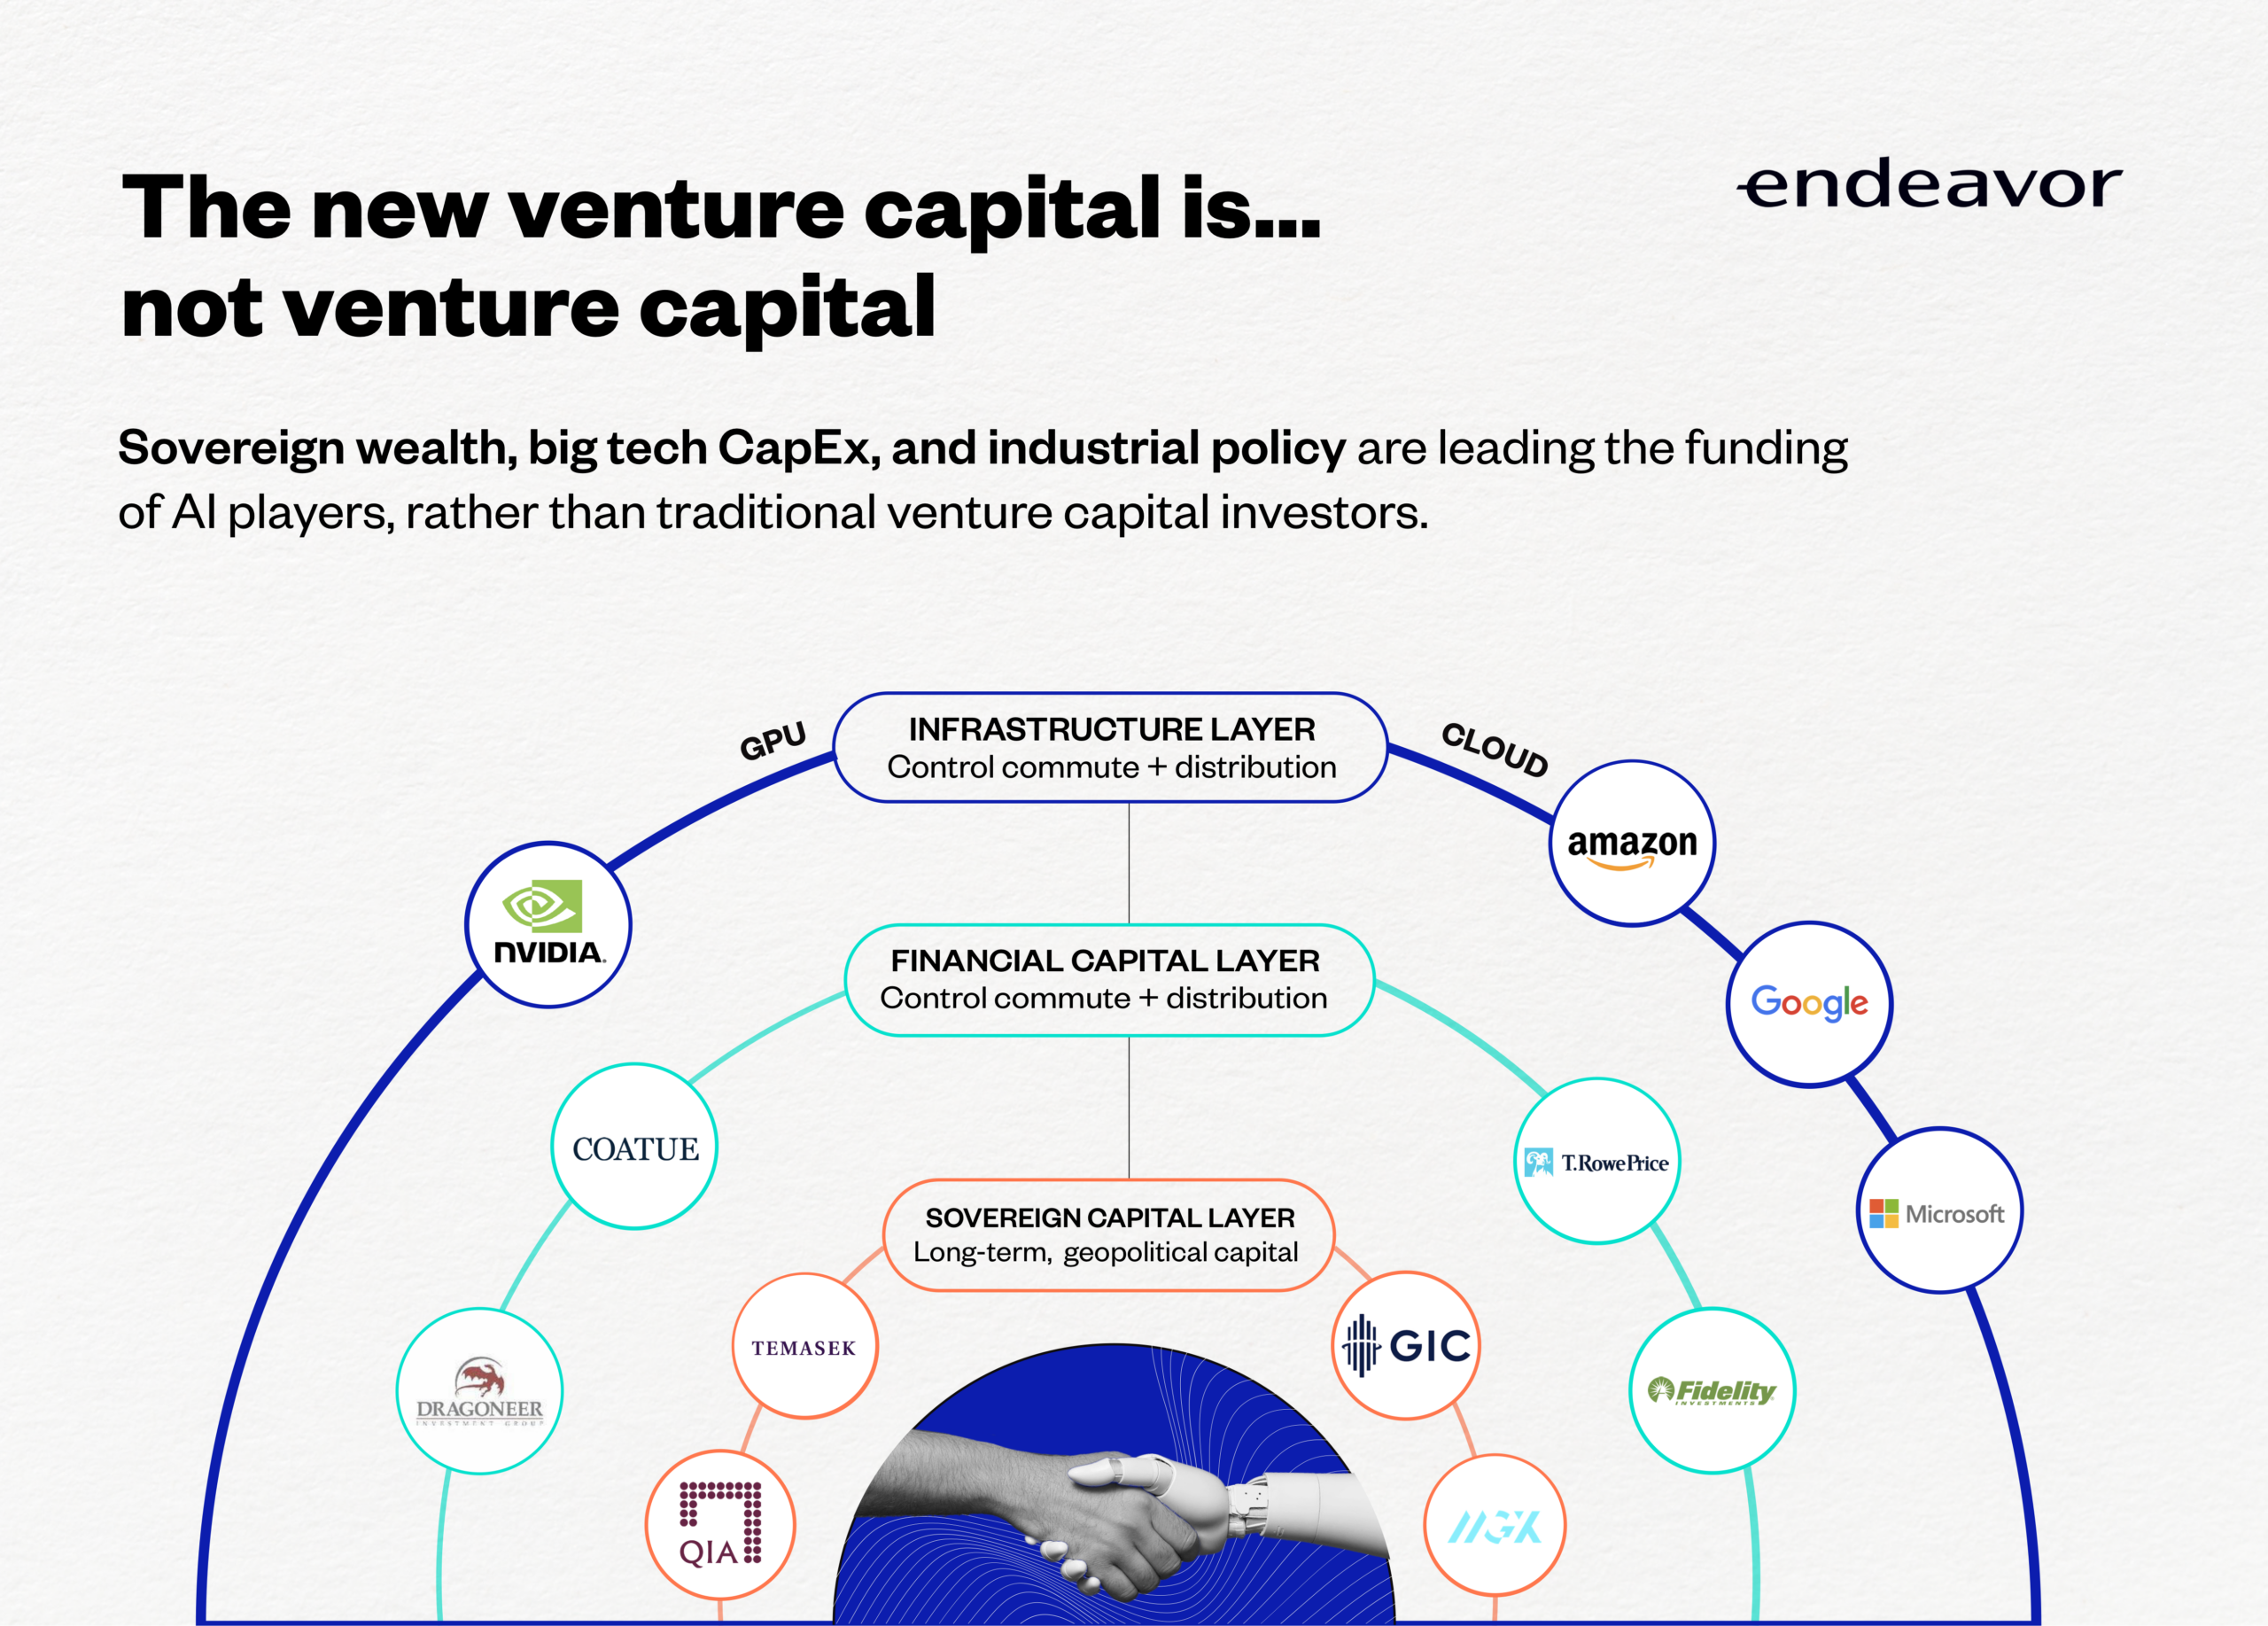
All of these investments get called venture capital. But when we drill down into the dollars, we see instead a mix of sovereign wealth deployment, big tech, capital expenditure, and even some industrial policy. This financing is important: it’s building global AI infrastructure, which needs to happen. But an exciting shift in technology is distorting the data and message around what’s happening in venture capital.
Leave the beta to California — and the alpha to the world
When we understand these three shifts, the data looks a little different.
It’s telling a story not of Californian dominance, but of a very particular movement in a very particular sector.
The big upcoming IPOs from Anthropic and OpenAI are a market signal as what we call venture capital readjusts and rebalances. Should we even still call this VC data, when it’s behaving so unlike traditional venture capital, pursuing such different goals, and made up of such different players? We’d argue no — and that in five years, we’ll probably be reading these numbers on a different chart under a different name.
Remember the $300B of venture capital invested in 2026’s first quarter, where 83% went to US companies? These four mega rounds from OpenAI, Anthropic, xAI, and Waymo — which as we’ve seen, weren’t really done by VC investors — make up 63% of that figure. Take those rounds out, and funding Elsewhere suddenly looks a lot brighter.
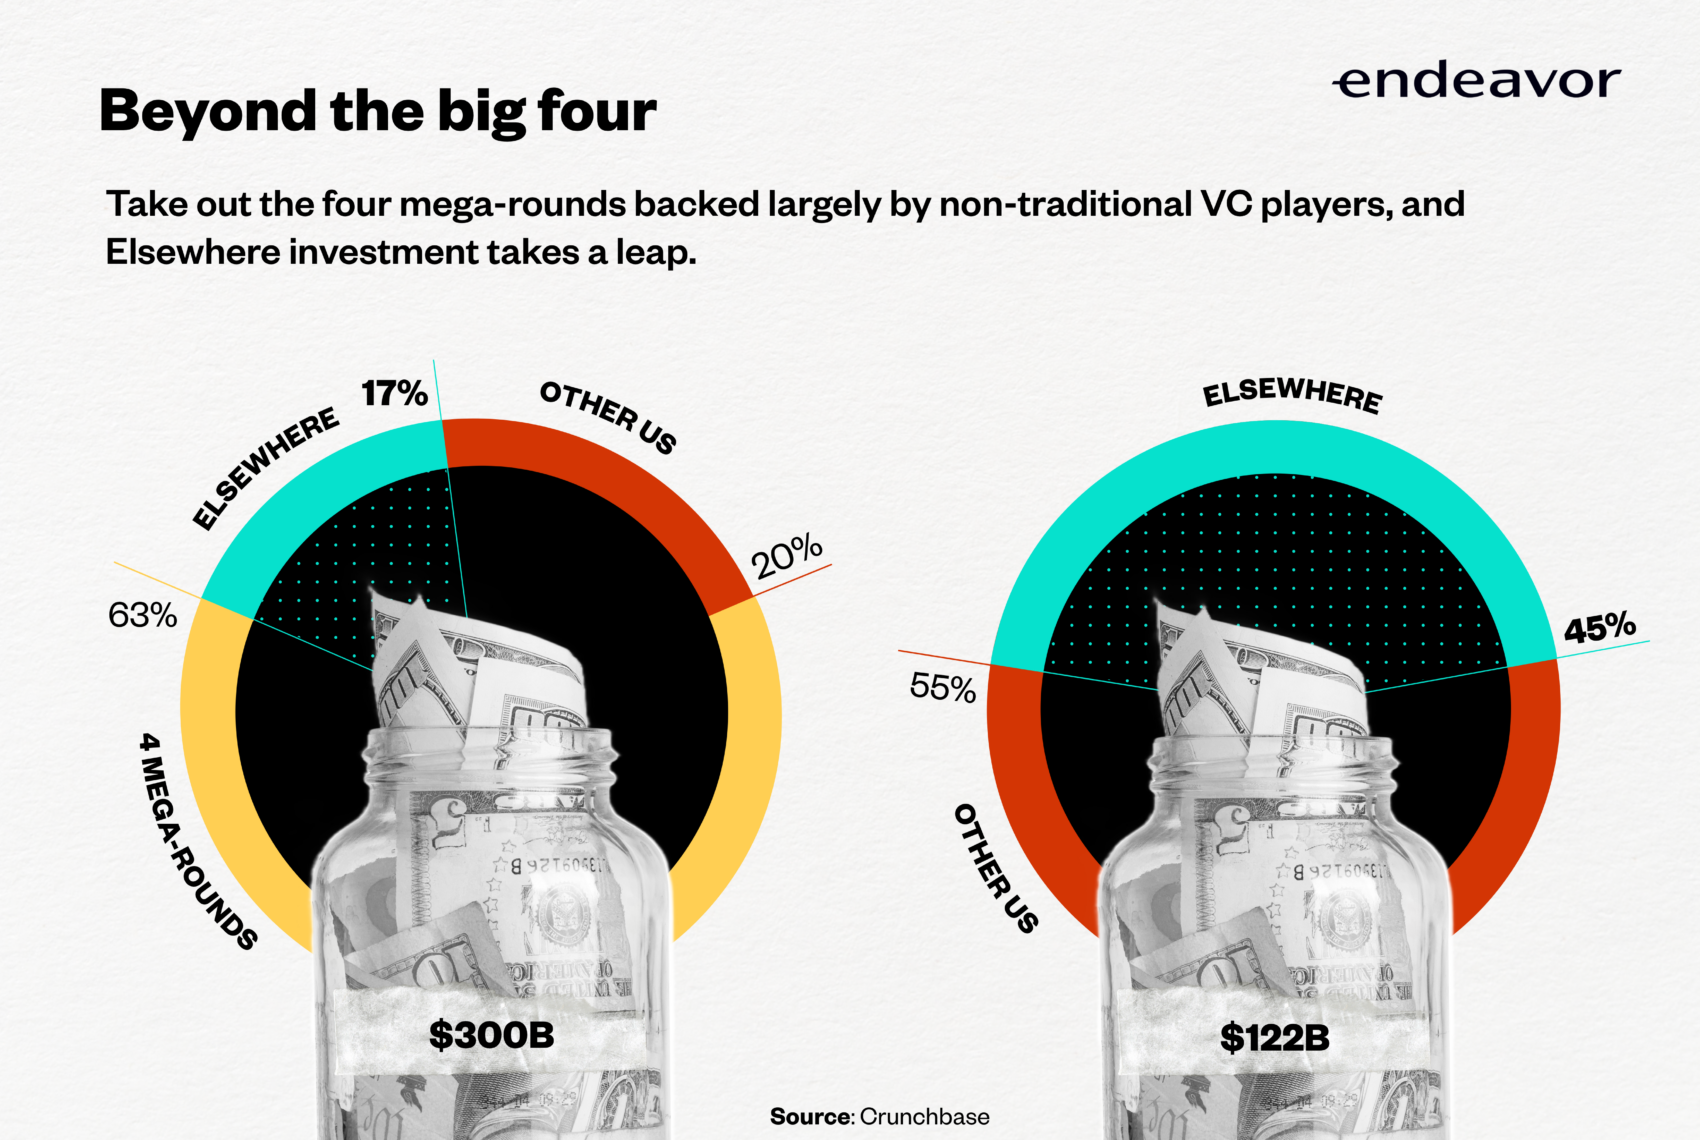
Minus those four anomalous rounds, funding outside the US goes up to around 45% of the global venture market. That keeps it on the strong growth rate we’ve been observing here at Endeavor for decades: from $5B a year invested Elsewhere in the 1990s to more than $180B a year today, a 40x growth over Endeavor’s lifetime.
Looking at deals, instead of dollars, also changes the pictures: about two-thirds of all venture capital deals over the past decade have taken place outside the US. That ratio largely isn’t changing.
Neither is our thesis. The rails that the big AI companies are building are highly significant, and the way venture capital is evolving to support them will change the landscape globally. But you don’t need to live in San Francisco to build the companies that are going to ride that wave to the next generation of success. Drop by for a visit, connect with those who can support your scale, learn from the scene… and then return to build Elsewhere.
Featured Stories
Unicorns aren’t the end of an ecosystem’s success. They’re the beginning.
Beyond Skyscrapers: What’s Really Powering Entrepreneurial Innovation in Dubai
Japanese entrepreneurs are leveling up: Endeavor CEO Linda Rottenberg explains how
The Collapse That Forced Proptech’s Boldest Founders to Reinvent Everything
Related Articles
Unicorns aren’t the end of an ecosystem’s success. They’re the beginning.
Beyond Skyscrapers: What’s Really Powering Entrepreneurial Innovation in Dubai